


How to Move Your No-Claim Discount to Your New Car
Just bought a new car and wondering what happens to the NCD you built up on the old one?
Your No-Claim Discount (NCD) belongs to you, not the car, so you can transfer it to an eligible replacement car. The transfer isn't automatic, though—you’ll need to arrange it with your insurance company. The process starts with withdrawing the NCD from the existing policy (ask your insurer to release it).
What happens next depends on whether you’re selling the old car, keeping it insured or have already bought insurance for the new one.

Check whether your NCD can transfer to a new car
NCD is the discount you earn for claim-free years. For private cars in Malaysia it is 25% after one claim-free year, rising to 55% after five or more claim-free years.
Before you apply for transfer, check these two conditions:
- Same owner and same policyholder. The car receiving the NCD must be registered and insured under your name. The reason: NCD is tied to you, so it cannot move to another person, not even to a spouse or family member.
- Same vehicle class. NCD can transfer from car to car, or from motorcycle to motorcycle, but usually not from a motorcycle to a car.
The industry association PIAM sets out this same-owner rule in its NCD guide. That means if you’re taking over ownership of a family member's car, for example, their NCD stays with them. You can ask your insurer to apply your own NCD to the car.
Find your situation and first step
The right first step depends on where you are in the changeover, so find your situation below.
| Situation | First step | What happens to the old policy | Watch for |
| You have already sold the old car | Tell the old car’s insurer you sold the car and want the cancellation processed as an NCD withdrawal | The policy is cancelled, so no extra premium is due on it | Ask for the withdrawal letter before you buy the new policy |
| You are keeping the old car and still need it insured | Tell the old insurer you want to withdraw the NCD but keep the old car covered | The old policy resets to 0% NCD and you pay a top-up for the remaining cover period | The top-up depends on your insurer, so ask what it will be |
| You are only switching insurer at renewal, for the same car | Ask the new insurer for a quote | Usually no special process is needed, as your NCD is shown when you get the quote | Check the quote shows the right percentage before you pay |
Already insured your new car before transferring the NCD?
Insurers handle this differently. Before arranging the transfer, ask the insurer covering your new car:
- Can it apply your existing NCD to that policy?
- What documents does it need?
- Would a premium adjustment or refund follow?
If you’re moving your NCD to another car, follow the steps below.
How to withdraw your NCD and use it on the new policy
The graphic below gives you a quick overview of the three main stages of an NCD transfer. The six steps that follow walk you through the process in more detail, starting with checking your current NCD. Your insurer will confirm its specific requirements, including the documents needed and how to submit your request.
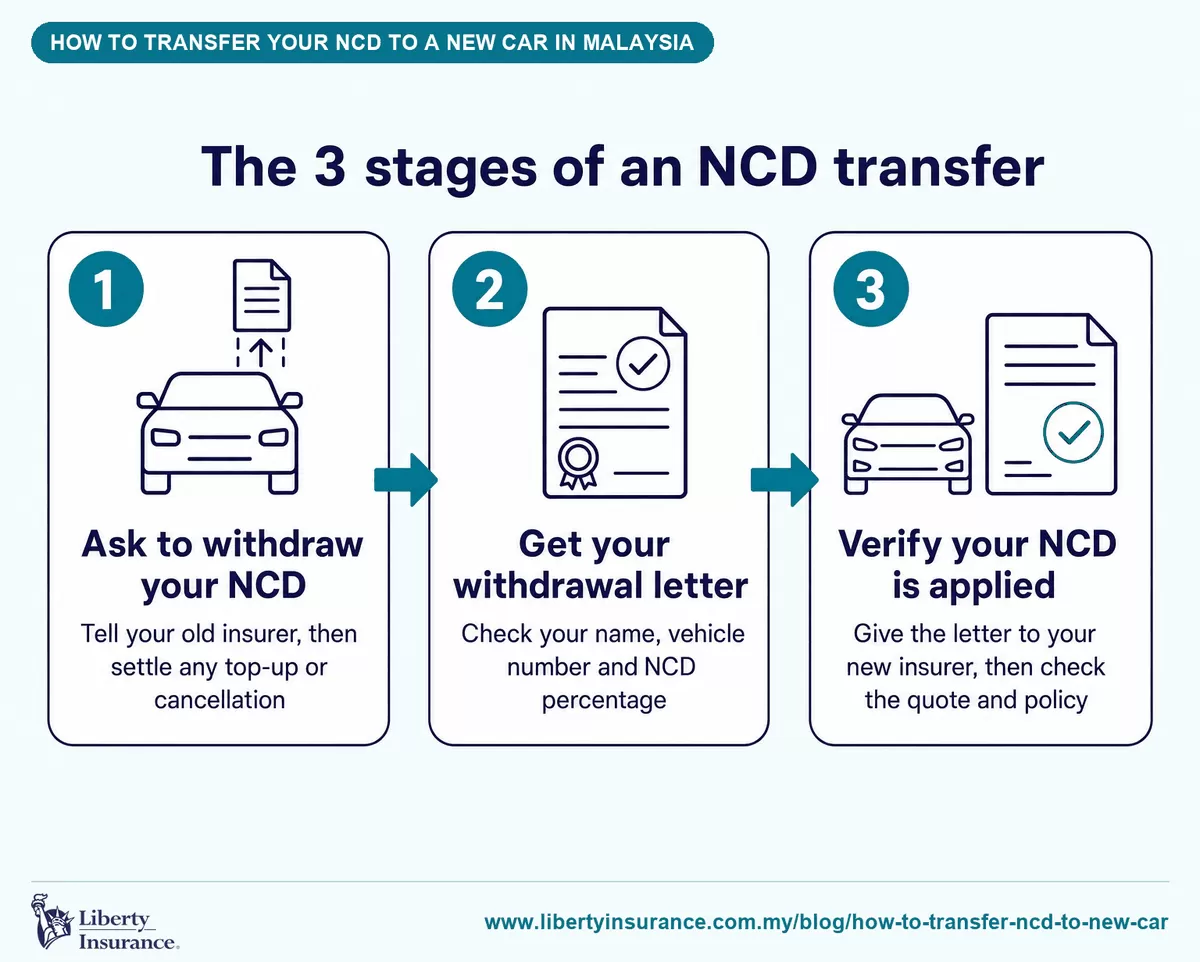
1. Check your current NCD percentage
Use the MyCarInfo NCD enquiry with your registration and identity card numbers to see your NCD report. Some insurers' online quote pages also show your NCD when you key in your details, usually nearer renewal.
Unsure where to find your policy details? See our guide to checking your car insurance status.
2. Tell the old insurer you want to withdraw your NCD
Withdrawing means removing your NCD from the old policy so it can be used on the new one. Give the insurer your old car’s registration number and policy number. Ask how to submit the request and which documents the insurer needs.
3. Settle any top-up, or cancel if the car is sold
If you keep the old car insured, the insurer usually recovers the discount for the remaining cover period, which you pay as a top-up. If you sold the car, ask for the cancellation to be processed as an NCD withdrawal.
4. Get confirmation that your NCD has been released
Ask for the NCD withdrawal confirmation letter or form, and check your name, vehicle registration number and NCD percentage.
Also, confirm the effective date of the withdrawal and the start date of the new policy, especially if you still need to drive the old car during the changeover.
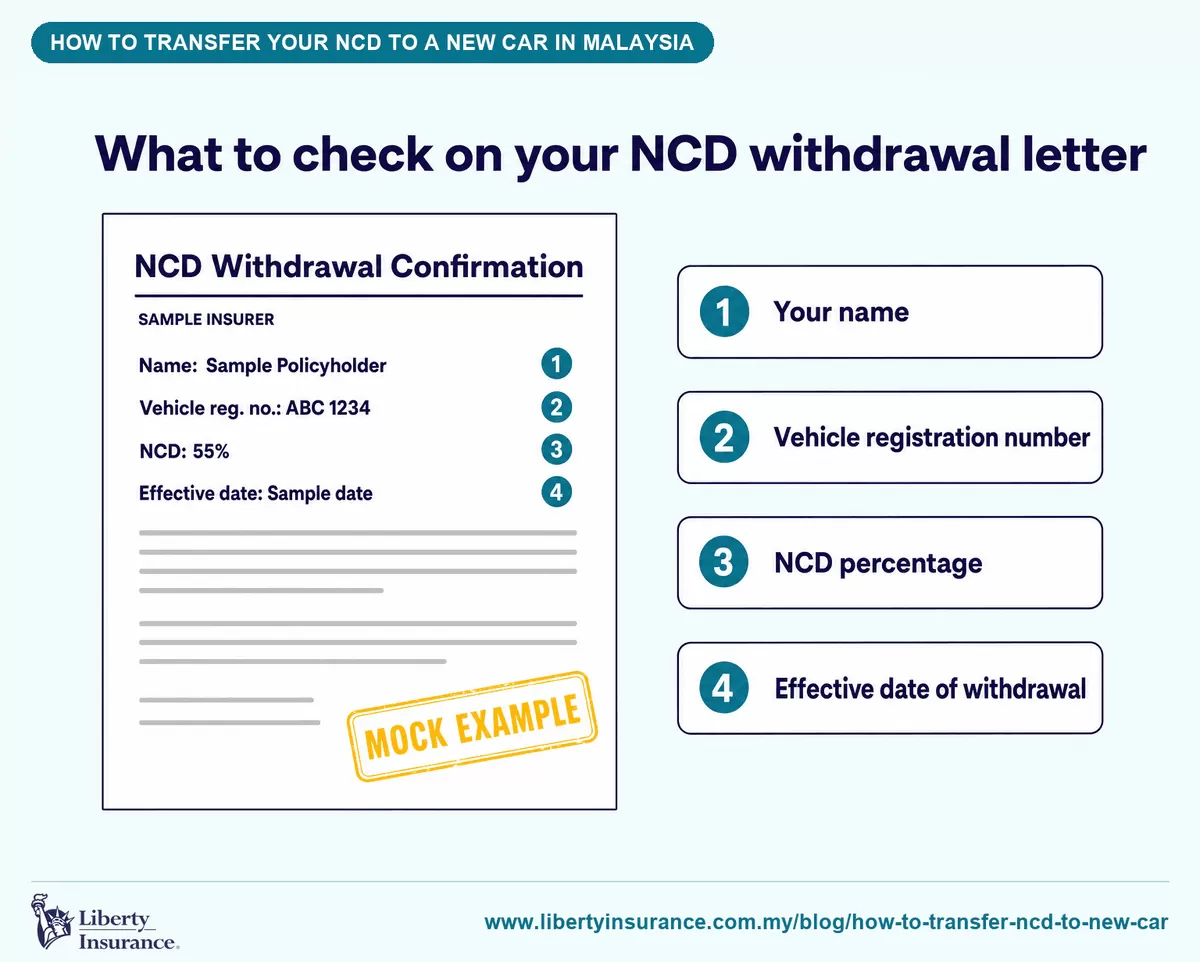
5. Give the withdrawal letter to your new car's insurer
Hand it to the new insurer or agent when you buy, or as soon as they ask for it.
6. Check the NCD before you pay for the new policy
Make sure the quote shows the expected percentage, then check it again on the policy schedule once issued. If it differs, ask the insurer to explain or correct it.
Why NCD withdrawal can mean a top-up payment
A common worry is why money is involved at all.
NCD is a discount rather than a cash balance, and it was applied to the old policy. When you withdraw it, the old policy resets the discount level to 0%. If that policy still has months to run and the car is still insured, the insurer usually recovers the discount for those remaining months.
That recovery is the top-up.
So, if you’ve sold the car and cancel the policy, this remaining-period NCD top-up does not apply. Ask your insurer to confirm the final cancellation adjustment, in this case.
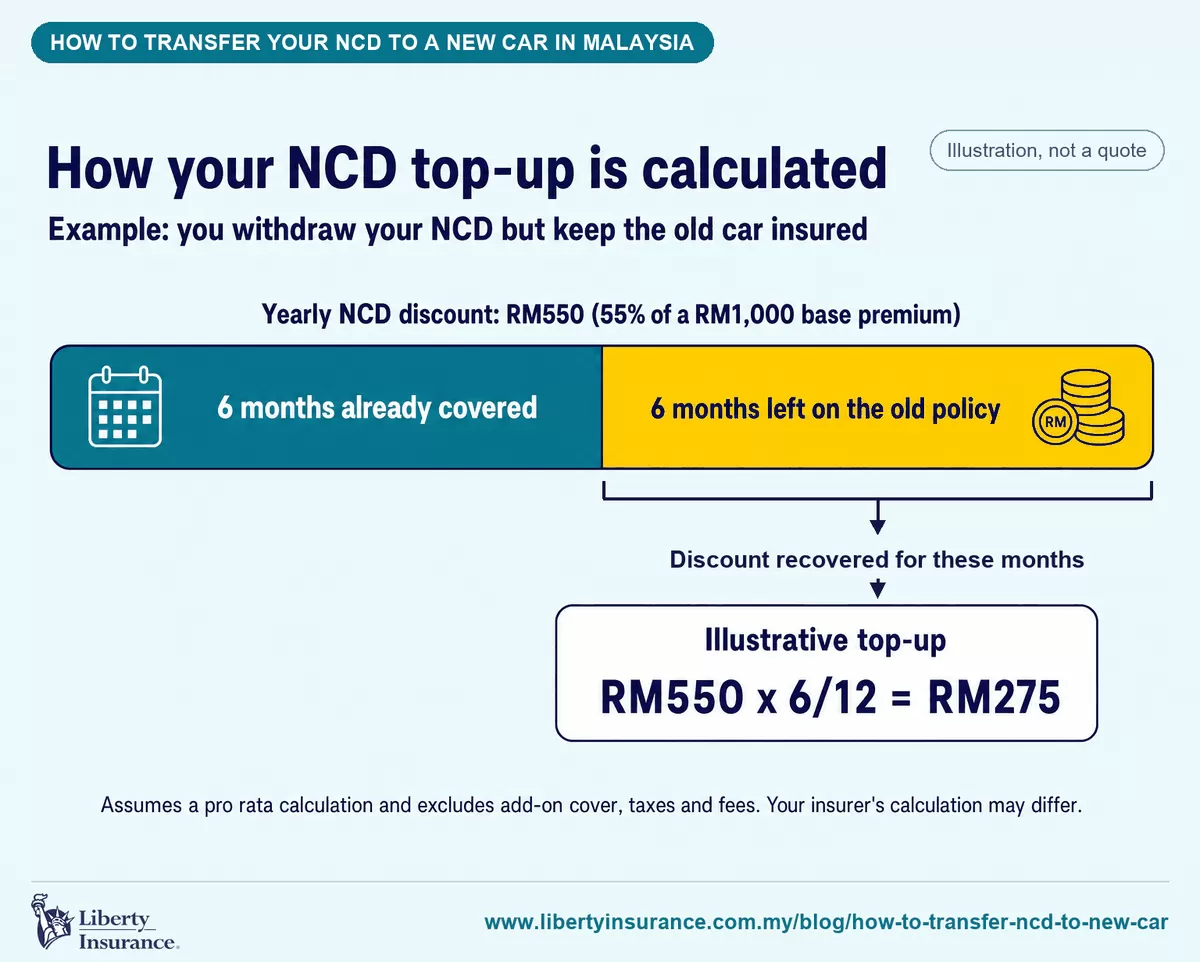
A simple top-up example
Assume the annual base premium is RM1,000:
- At 55% NCD, the annual discount or premium savings is RM550.
- The premium after NCD is RM450, before other charges.
If six months are left on the old policy and the insurer calculates the adjustment proportionately (prorated), the illustrative top-up is:
RM550 × 6/12 = RM275
This example excludes add-on cover, taxes and fees. Ask your insurer for the actual adjustment and applicable terms.
Common NCD transfer mistakes to avoid
- Assuming the dealer or agent has completed the transfer. If a dealer or agent is handling it, ask for confirmation that the NCD has been released and applied to the new policy. Check the percentage yourself before paying.
- Assuming a family member's NCD comes with their car. It doesn't, because NCD follows the named policyholder. If you take over a parent's or sibling's car, your own NCD is what applies.
- Letting the NCD sit unused. If you stop renewing your insurance, insurers step your NCD down for each year you do not renew until it reaches zero. Ask your insurer how long your withdrawn NCD stays valid before you delay.
- Not keeping a record of your NCD. Save the withdrawal confirmation and check that the quote and issued policy show the expected percentage. These records will help if you need to query a discrepancy.
Frequently asked questions
Can I transfer my NCD to my spouse or another person?
No. NCD belongs to the named policyholder and moves only to a vehicle insured under the same name. If a family member sells you their car, their NCD stays with them and doesn't come with the car.
Can I transfer my NCD online?
Ask your current insurer whether it accepts NCD withdrawal requests online or by email, or whether you need to go through an agent or branch. MyCarInfo lets you check your NCD; the withdrawal itself must be arranged with your insurer.
What happens to my NCD if I sell my car?
Your NCD stays with you. Tell your insurer you sold the car and ask for the cancellation to be processed as an NCD withdrawal. The insurer will issue a withdrawal letter, which you then give to the insurer of your new car.
Will I keep the same NCD percentage after transferring it?
The transfer itself does not reduce your eligible NCD percentage. However, the amount you save can change because the new car’s premium may be different, especially if you’re switching to a higher-value car. Check the percentage on your new quote before paying.
Why do I have to pay when I withdraw my NCD?
You are paying back the discount for the remaining cover period on the old policy, not paying a penalty. Withdrawing resets that policy to 0%, so the insurer usually recovers the discount for the months that are still covered. If the old policy is cancelled because the car is sold, no extra premium is due on it.
Can I transfer NCD from a motorcycle to a car?
Usually not. NCD normally moves within the same vehicle class, which means car to car and motorcycle to motorcycle. If you are changing vehicle type, ask your insurer what applies to your case.
How long can I wait before using my NCD on a new car?
Insurers step unused NCD down each year you do not insure, until it reaches zero after several years. Reported grace periods vary, so ask your insurer how long your withdrawn NCD stays valid.
Can I transfer my NCD after buying insurance for my new car?
Your insurer may be able to apply the NCD to your existing policy. Ask what documents are needed and whether you’re eligible for a premium refund.
Arranging insurance for your next car?
Explore Liberty’s car insurance options and confirm how to apply your existing NCD before purchasing your policy.
Disclaimer: The information in this article is provided for general awareness purposes only. While we endeavour to ensure the content is accurate at the time of publication, we make no representation or warranty as to its completeness, accuracy, or suitability for any particular purpose.
Liberty General Insurance Berhad is a member of Perbadanan Insurans Deposit Malaysia (PIDM). PIDM protects the benefit(s) payable under the eligible policy up to protection limits. Please refer to PIDM's TIPS Brochure or PIDM's Website, or contact our customer service.